Hungary's Wekerle+: 3% and 5% home loans, a new home-savings scheme and a renovation programme – what the government announced on 27 October, in numbers
HUF 50 million, 25 years, five years' mandatory residence, up to HUF 1.8 million in state support over ten years, and a 30–50% non-repayable share for renovations. What is settled, what awaits detail, and what two percentage points mean for a monthly instalment – with sources, without advice.
On Tuesday 27 October 2026, Prime Minister Péter Magyar, Economy and Energy Minister István Kapitány and Finance Minister András Kármán announced the details of Hungary's Wekerle+ programme. According to Portfolio's live coverage (in Hungarian), the package has three parts: a loan for buying or building a home, a home-savings scheme, and an energy renovation programme. This article summarises the announced figures, explains the concepts and notes what still awaits detail. It is not advice: the final terms are set by the decree and by the banks.
| Fact sheet | |
|---|---|
| Announced | 27 October 2026 |
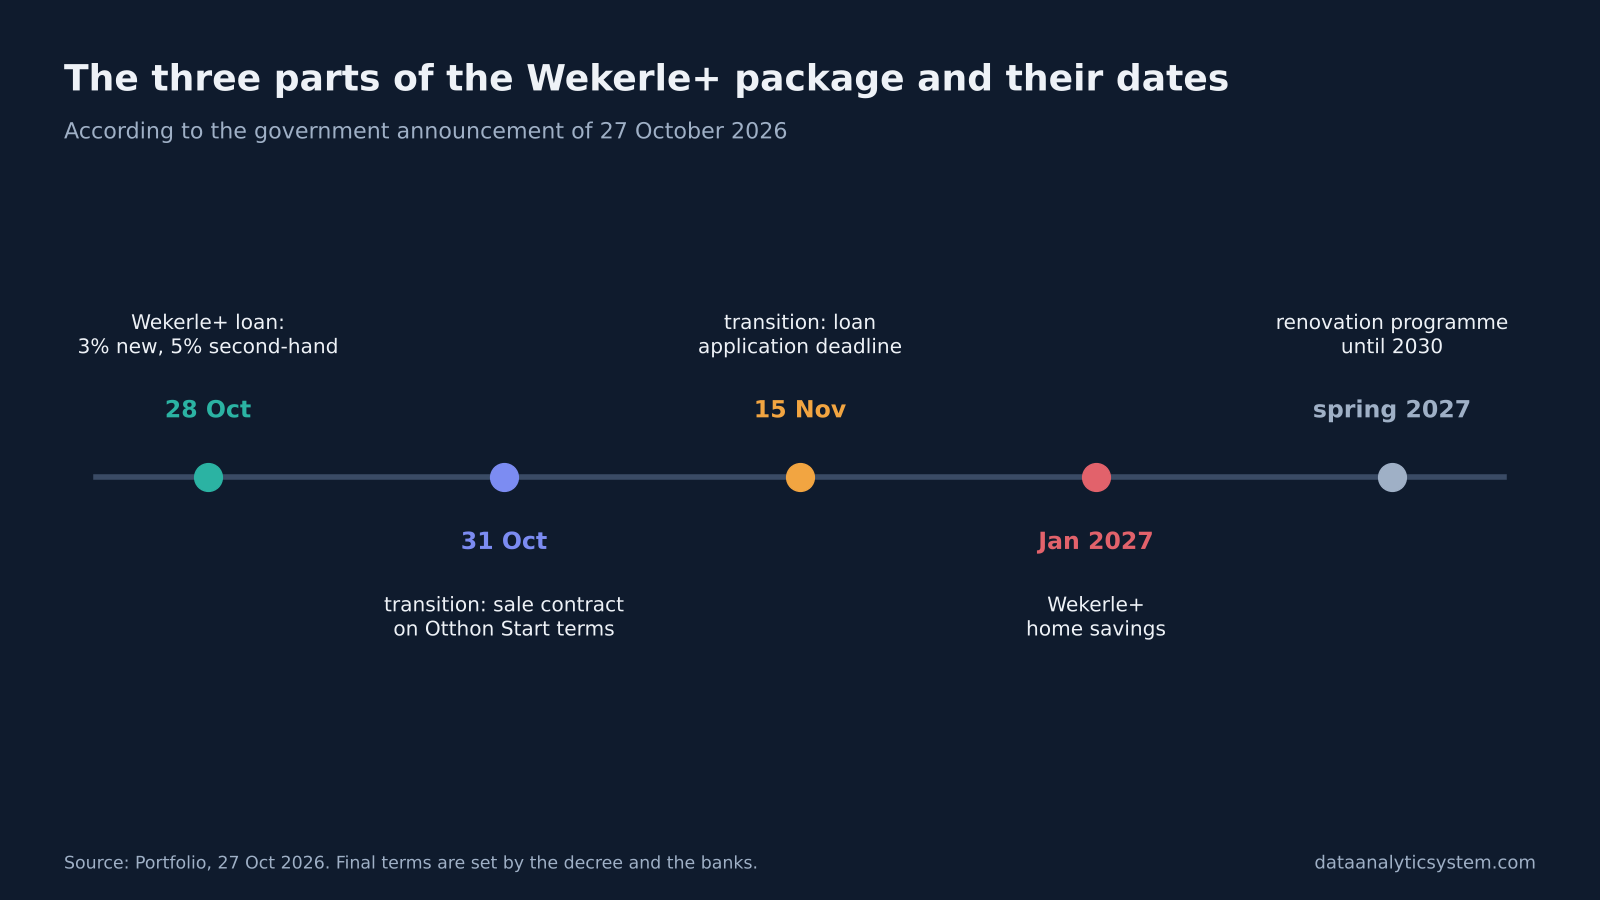
| Wekerle+ loan starts | 28 October, replacing Otthon Start |
| Rate | fixed 3% for new homes, fixed 5% for second-hand homes |
| Age | 18–45 |
| Amount, term | up to HUF 50 million, up to 25 years |
| Home savings | from January 2027, up to HUF 1.8 million state support over ten years |
| Renovation programme | from spring 2027, until 2030 |
Source: Portfolio, 27 Oct (in Hungarian).
1. The Wekerle+ loan
According to Portfolio, the announced conditions are:
- Rate: 3% for newly built homes, 5% for second-hand homes, both fixed.
- Age: between 18 and 45. Earlier press material, such as Bankmonitor's calculations, still used an upper limit of 41.
- Price caps: HUF 100 million for a flat, HUF 150 million for a house, and at most HUF 1.5 million per square metre; indexed from 2028.
- Ownership: an existing home share of 50% or more excludes applicants; exceptions are a property worth under HUF 30 million and an inheritance encumbered by usufruct.
- Commitment: five years' mandatory residence; the home may not be rented out or used as an office.
- Not required: marriage or having children. A parent or sibling may join as co-debtor.
According to András Kármán, VAT on newly built homes stays at 5% indefinitely.
The transition rule
According to the announcement, anyone who has already signed a sale contract may still apply under Otthon Start terms. A Facebook post by Péter Magyar that afternoon, as reported by Portfolio, clarified: sale contracts may be signed until 31 October and loan applications submitted until 15 November. Otthon Start loans already concluded remain valid unchanged.
What two percentage points mean for an instalment
Bankmonitor's example for a HUF 30 million, 25-year loan:
| Rate | Monthly instalment |
|---|---|
| 3% (new home) | HUF 142,263 |
| 5% (second-hand home) | HUF 175,377 |
The difference is HUF 33,114 a month, almost HUF 10 million over the full term. It is an illustration, not a bank offer or a personal calculation.
2. The Wekerle+ home-savings scheme
According to Portfolio, it starts in January 2027. State support is 10% of deposits in the first five years, up to HUF 10,000 a month, and 20% in the second five years, up to HUF 20,000 a month. With deposits of HUF 100,000 a month, that is HUF 120,000 and then HUF 240,000 a year – HUF 1.8 million over ten years. The previous scheme, closed in 2018, supported deposits of HUF 20,000 a month. Portfolio's example calculation says that at a 3% deposit rate up to HUF 16 million could accumulate over ten years; this depends on the assumed rate.
3. The Wekerle+ renovation programme
According to Portfolio:
| Property | Loan | Rate |
|---|---|---|
| Family house | HUF 15 million | fixed 3% |
| Flat in a condominium | HUF 5 million per flat | 0%, 15–20 years |
| Prefab-block flat | HUF 4 million per flat | 0% |
The non-repayable share depends on the building's energy rating: categories A–C get a loan only, D–G get 30%, and for H–I half of the loan can be written off. The condition is a primary-energy saving of at least 30%. Own contribution is at most HUF 500,000 for a house and HUF 200,000 per flat. The budget is HUF 633 billion until 2030, mainly from EU cohesion funds; another part of the source says HUF 600 billion. The aim is to renovate at least 30,000 homes a year. For houses, one part of the source gives February 2027 as the start, another March; for condominiums, March.
5 things many people don't know
- "Primary energy" is not the electricity bill. It measures total energy use from production onwards; renovation must cut it by at least 30%.
- A worse rating brings more support. In categories H–I, half the loan can be written off.
- Condominiums need a change in the law. According to Portfolio, the condominium act must be amended for joint borrowing.
- The age limit went up. Earlier calculations used 41 years; the announcement says 45.
- Renovation loans won't only come from bank branches. According to Portfolio, the expanded MFB Pont network and commercial banks will both distribute them, with 70–80 energy advisers.
Summary
- Wekerle+ loan from 28 October: 3% for new and 5% for second-hand homes, ages 18–45, up to HUF 50 million.
- Transition: contracts until 31 Oct, applications until 15 Nov under Otthon Start terms.
- Home savings from January 2027, up to HUF 1.8 million support over ten years.
- Renovation from spring 2027, a 30–50% non-repayable share depending on rating.
- The final details are set by the decree and the banks.
Related reading: Wekerle Plus: the Otthon Start successor · Renovation before and after: how to document the work · Blog archive.
Educational content. Not financial, lending or property-buying advice. This article describes press coverage of the government announcement of 27 October 2026; the final terms are set by law and by the lenders. Data Analytic Investments is not affiliated with government bodies, MFB or the portals cited. Images labelled "AI illustration" are not photographs.
Continue on DAI
Explore Topics
Written by
Data Analytic Investments
Content creator and writer sharing insights and stories.