Wekerle Plusz: what we know about the successor to Hungary's Otthon Start – 3 and 5 percent, an age limit of 41, home savings and renovation loans
What changes compared with Otthon Start, who qualifies, how much more a 40-million-forint loan costs per month, what happens to home savings and the renovation scheme – and which questions have no answer yet. With sources, without forecasts.
On 19 October 2026 Prime Minister Péter Magyar told parliament that from 2027 a programme called Wekerle Plusz will replace Otthon Start, Hungary's fixed 3% home-loan scheme. The package has three parts: a subsidised loan tied to a first home, a revived state top-up for home savings, and an energy renovation programme. This article collects what is known so far and what is not. The final rules will be set out in a government decree.
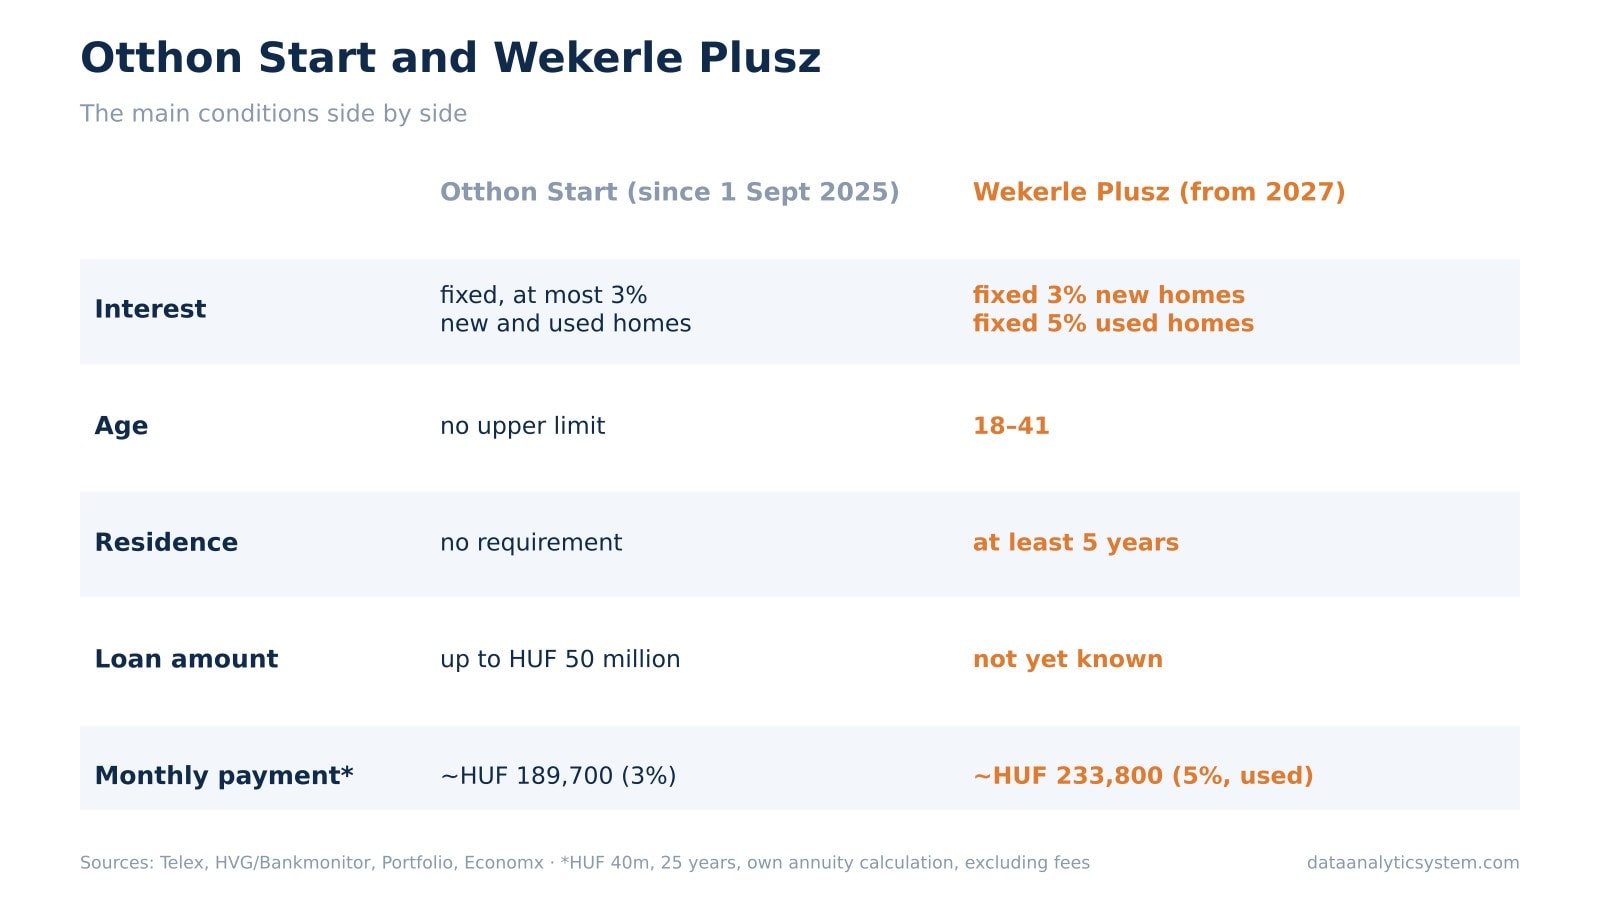
| Fact sheet | Otthon Start (since 1 Sept 2025) | Wekerle Plusz (from 2027) |
|---|---|---|
| Interest | fixed, at most 3%, new and used homes | fixed 3% new homes, fixed 5% used homes |
| Age | no upper limit | 18–41 |
| Residence | no requirement | at least 5 years |
| Other property | at most one, with a 50%+ share | stricter, also applies to the spouse |
| Loan amount | up to HUF 50 million | not yet known |
Sources: Telex, HVG / Bankmonitor, Portfolio (all in Hungarian).
The key difference
Otthon Start gave a uniform fixed rate of at most 3% on new and used homes alike. Wekerle Plusz splits this in two: fixed 3% for new homes and fixed 5% for used ones. Eligibility also narrows. According to Telex's summary:
- applicants must be aged 18 to 41;
- buyers must move into the home and live there for five years;
- neither the applicant nor their spouse may hold a 50% or larger share in another property;
- bank commissions will be cut significantly;
- Otthon Start contracts already signed remain valid.
According to Bankmonitor's analysis, the five-year residence rule excludes buy-to-let purchases.
The monthly difference
A simple annuity calculation for the two rates: HUF 40 million, 25 years, fixed rate, monthly repayments.
| Rate | Monthly payment (approx.) | Total over 300 months |
|---|---|---|
| 3% | HUF 189,700 | HUF 56.9 million |
| 5% | HUF 233,800 | HUF 70.2 million |
| Difference | ~HUF 44,100 | ~HUF 13.2 million |
Calculated with the standard annuity formula, excluding fees; not a bank offer. Economx gives about HUF 44,000 a month and about HUF 13 million in total for the same example.
Portfolio, citing a linked analysis, mentions a 19–23% rise in monthly payments and says 35–50% of those eligible for the subsidised loan could drop out. It adds that the market effect may be smaller, because Otthon Start had also crowded out unsubsidised mortgages.
Home savings: the state top-up returns
A scheme abolished in 2018 comes back in a new form. According to Telex, people who save regularly for five or ten years receive a non-refundable state top-up: 10% in the first five years and 20% from year six, on top of 3% bank interest. The old scheme paid 30% a year, capped at HUF 72,000.
Energy renovation, now for panel flats too
- Loan: the cap on the fixed 3% renovation loan rises from HUF 6 million to HUF 15 million.
- Grant: 30–50% of the cost, up to HUF 7.5 million, depending on the property's current energy state. At least 30% energy savings are required.
- Who: nationwide, regardless of age, marital status or children. Economy Minister István Kapitány said residents of panel blocks can apply too.
- What for: insulation, window replacement, heating upgrades.
- Aim: 20,000 households a year, with about HUF 40 billion in support.
On the supply side, the Wekerle Sándor housing and dormitory programme starts in 2027 with HUF 30 billion of EU funds, with EUR 550 million planned for the following three years.
What stays the same in 2027
According to Telex, the 5% VAT on new homes, the Babaváró loan, CSOK, rural CSOK and the utility price caps all remain.
5 things many people don't know
- The name belongs to a prime minister. Sándor Wekerle was Hungary's first prime minister of non-noble, middle-class origin; the Wekerletelep garden suburb in Kispest is named after him too.
- The start date is not known. The first of Bankmonitor's eight open questions is when Otthon Start closes, and whether the deadline refers to the sales contract, the application or the loan contract.
- The price cap was tight. According to MNB data, only 14.2% of new-build flats in Budapest fitted within Otthon Start's price and per-square-metre limits in Q1 2026.
- Some banks currently go below the statutory rate. Some offer 2.75–2.80% on Otthon Start loans plus cashback of several hundred thousand forints; whether that survives is still open.
- Unmarried couples are a question mark. Current rules do not allow cohabiting partners to apply jointly; under the new scheme this is not yet decided.
Summary
- From 2027, Wekerle Plusz: 3% for new homes, 5% for used ones, ages 18–41, 5 years of residence.
- HUF 40 million over 25 years: the gap between the two rates is about HUF 44,000 a month.
- The home savings top-up returns (10%, 20% from year six); the renovation loan rises to HUF 15 million.
- Still open: start date, loan amount, maximum term, price caps.
Related reading: Otthon Start one year on · Blog archive.
Educational content. Not financial or investment advice; before any loan decision, the bank's official information and the published decree apply. Data Analytic Investments is not affiliated with the government, any bank or the portals cited. Images labelled "AI illustration" are not photographs.
Continue on DAI
Explore Topics
Written by
Data Analytic Investments
Content creator and writer sharing insights and stories.