Otthon Start's final days and Wekerle Plus's first banks: deadlines, rates and conditions in one place
Two subsidised loan schemes run side by side for a few days. The two Otthon Start deadlines, what the first bank offers under Wekerle Plus, and what the decree sets out – with sources, without forecasts.
The decree for Wekerle Plus, Hungary's new subsidised home loan, took effect on 28 October, and Otthon Start, the fixed 3% scheme it replaces, closes at the end of the month. For a few days, two state-backed home loans exist side by side. On 29 October the first banks moved: Raiffeisen began accepting applications and Erste opened pre-registration. This article sets the deadlines and conditions side by side. The announcement of the scheme was covered in an earlier article; the subject here is the practical side of the switch.
| Fact sheet | |
|---|---|
| Otthon Start: purchase contract | by 31 October 2026 at the latest |
| Otthon Start: loan application | by 15 November 2026 at the latest |
| Wekerle Plus in force | 28 October 2026 (Decree 298/2026) |
| Wekerle Plus maximum | HUF 50 million, up to 25 years |
| Rate paid by the borrower | at most 3% new, at most 5% used homes |
| Raiffeisen APR | 3.04% new, 5.12% used homes |
Sources: Bankmonitor, on the decree, Bankmonitor, 29 Oct, Portfolio, 29 Oct (all in Hungarian).
Two dates for Otthon Start
The phase-out of Otthon Start has two deadlines, and they measure different things.
- 31 October. The purchase contract must be signed by this date. According to the Bankmonitor summary, applications already accepted or under assessment are not affected by the change.
- 15 November. The loan application must be submitted by this date. According to Portfolio, Erste expects heavier customer traffic before the deadline.
There are 15 days between the two dates (own calculation). Another Bankmonitor article lists what banks typically ask for in this window: a social-security certificate (through the state's DÁP app the usual processing time is 8 days, and it is valid for 30 days), an energy performance certificate, an employer's statement, the contract and proof of its filing, three months of bank statements, declarations and valid ID documents. Booking an appointment does not by itself count as submitting an application.
What the Wekerle Plus decree sets out
Bankmonitor highlights these main points from Decree 298/2026:
- Age: applicants must be between 18 and 45.
- Amount and term: at most HUF 50 million, at most 25 years.
- Rate: at most 3% for new homes and construction, at most 5% for used homes.
- Fees: the early repayment fee is capped at 1% of the amount repaid; the bank's arrangement fee is capped at HUF 30,000, plus the valuation.
- First home: owning less than 50% of a residential property generally does not disqualify; properties worth under HUF 30 million are disregarded.
- Property: the price cap is HUF 100 million for a flat and HUF 150 million for a detached house; the price per square metre of useful floor area may not exceed HUF 1.5 million.
- Obligations: borrowers must move in within 180 days and live there for 5 years.
- Unmarried couples: may apply jointly, and both must acquire ownership.
Bankmonitor notes that some points are its own interpretation and that banks' final conditions may differ.
What the first bank offers
According to Bankmonitor's 29 October article, Raiffeisen's terms are:
| Item | New home | Used home |
|---|---|---|
| Contractual rate | 5.78% | 5.78% |
| State interest subsidy | 2.78 percentage points | 0.78 percentage points |
| Rate paid by the borrower | 3% | 5% |
| APR | 3.04% | 5.12% |
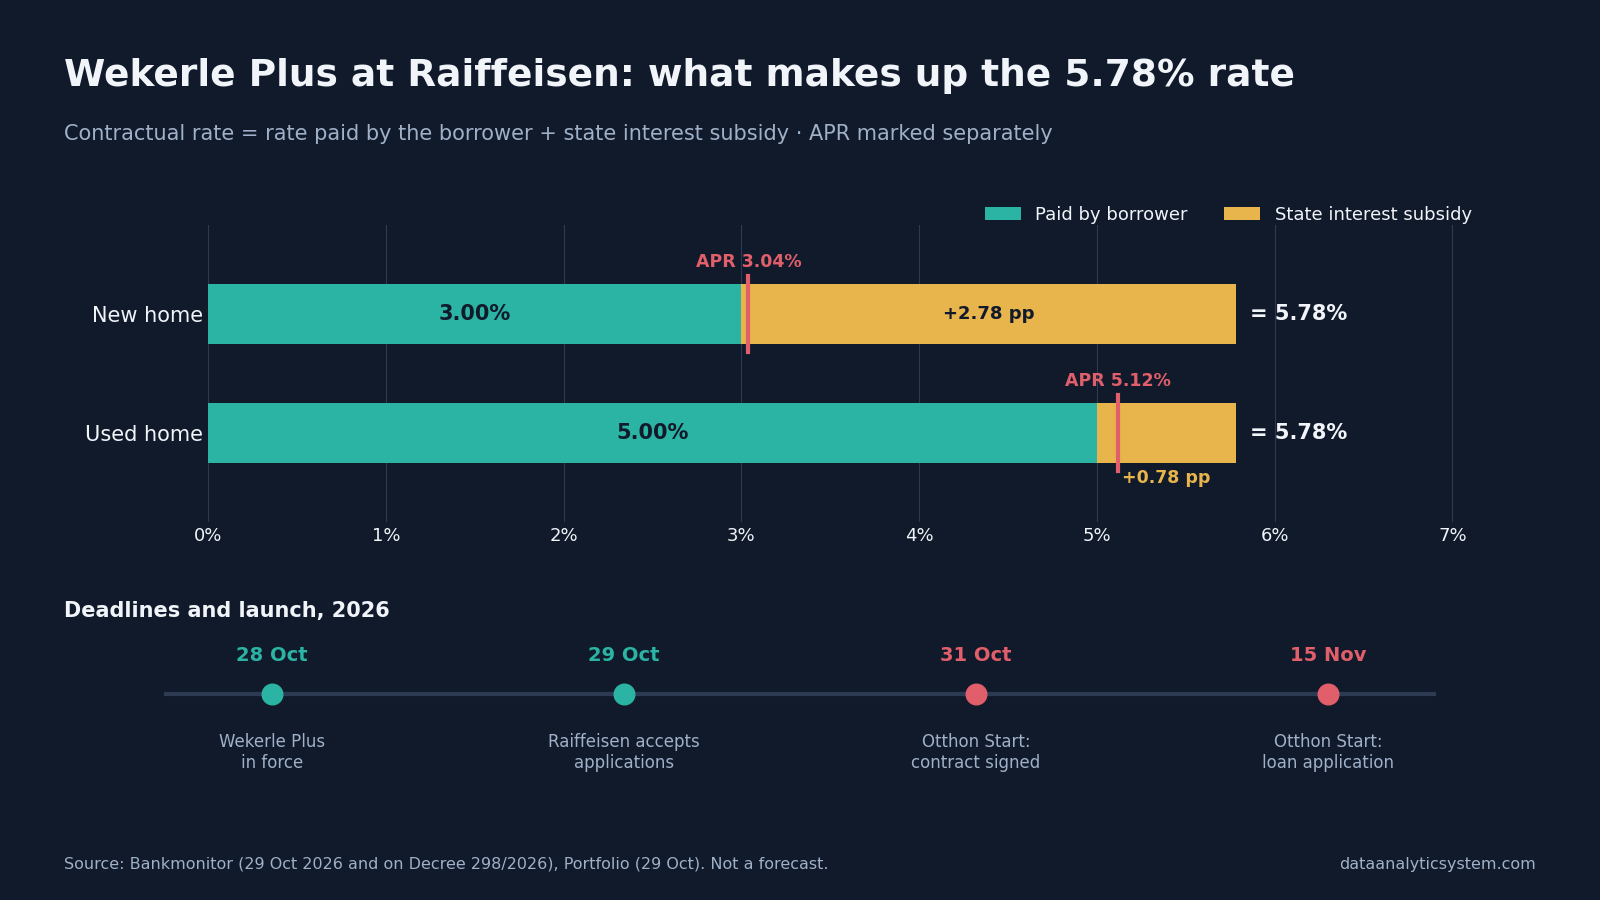
The contractual rate is tied to the market rate on 5-year Hungarian government bonds plus 0.5 percentage points, and is reset every 5 years. The state subsidy runs for at most 25 years. The assessment fee is 0.75% of the amount disbursed, capped at HUF 30,000. If the loan is closed within three years, or the balance falls below half the amount disbursed, the bank may charge the waived fees afterwards.
Where the other banks stand
- Erste: opened pre-registration on 29 October. This is not a formal application: customers can ask for a notification or a call-back. The bank plans to start accepting applications the following week.
- Other banks: the sources opened for this article did not give exact start dates for the other large banks. Banks are still building the decree into their systems.
How to read this week
The two schemes tie eligibility to different dates. For Otthon Start, the day the contract is signed counts; for Wekerle Plus, the application must be filed within 180 days of the contract. Banks have 30 days to assess a purchase loan and 60 days for construction, not counting time spent on missing documents. The schemes' conditions differ: the rate on used homes, the age limit, and Wekerle Plus's property-value caps. Which one fits a given situation depends on personal circumstances; this article does not weigh that.
5 things many people don't know
- APR is not the same as the rate. At Raiffeisen the borrower pays 3% on a new home, but the APR is 3.04% because fees are included.
- Pre-registration is not an application. Erste's form only requests a notification or call-back.
- A property under HUF 30 million is disregarded. In Bankmonitor's reading, lower-value ownership does not count against first-home status.
- Price and valuation may differ. Under the decree, by at most 20%.
- The social-security certificate expires. According to Bankmonitor it is valid for 30 days, so timing matters.
Summary
- Otthon Start: contract by 31 October, application by 15 November.
- Wekerle Plus has been in force since 28 October: up to HUF 50 million, 3% for new and 5% for used homes.
- The first bank, Raiffeisen, has accepted applications since 29 October, at 3.04% and 5.12% APR.
- Erste opened pre-registration; applications are expected the following week.
- Contradiction in the sources: a 24 October report (mfor.hu) mentioned an age range of 18–41, while summaries of the published decree give 45.
Related reading: Wekerle Plus announcement in numbers · MNB house price index, Q3 · Blog archive.
Data Analytic Investments is not affiliated with the banks or portals cited; names are used for identification only. Final conditions are those given by the chosen bank.
Educational content. Not investment advice.
Continue on DAI
Explore Topics
Written by
Data Analytic Investments
Content creator and writer sharing insights and stories.