A Fed decision and Big Tech earnings in one week: what is on the calendar from 26 to 30 October, and how to read futures-market probabilities
About a third of S&P 500 companies report this week, third-quarter profit growth is tracking above 32%, and futures priced about a 5% chance of a hike on Wednesday. What these numbers mean – with sources, without forecasts.
The week starting 26 October is one of the busiest of the year for US markets. According to Reuters' Sunday preview, the Federal Reserve (Fed) meets while about a third of S&P 500 companies report quarterly results, including Alphabet, Microsoft and Amazon. This article summarises the calendar and the background numbers and explains the concepts. It does not forecast rates and does not assess any stock.
| Fact sheet | |
|---|---|
| Fed meeting | Wednesday 28 Oct; decision 2:00 pm, press conference 2:30 pm (US Eastern) |
| Central European time | 7:00 pm and 7:30 pm (this article's conversion) |
| September | the Fed raised rates, its first hike since 2023 |
| Chance of a hike on Wednesday | about 5% (futures, late Thursday) |
| Chance of a hike in December | about 80% |
| S&P 500 companies reporting | about one third |
| Q3 profit growth | above 32% year on year (LSEG IBES) |
Sources: Reuters via Business Recorder, 26 Oct, Kiplinger economic calendar.
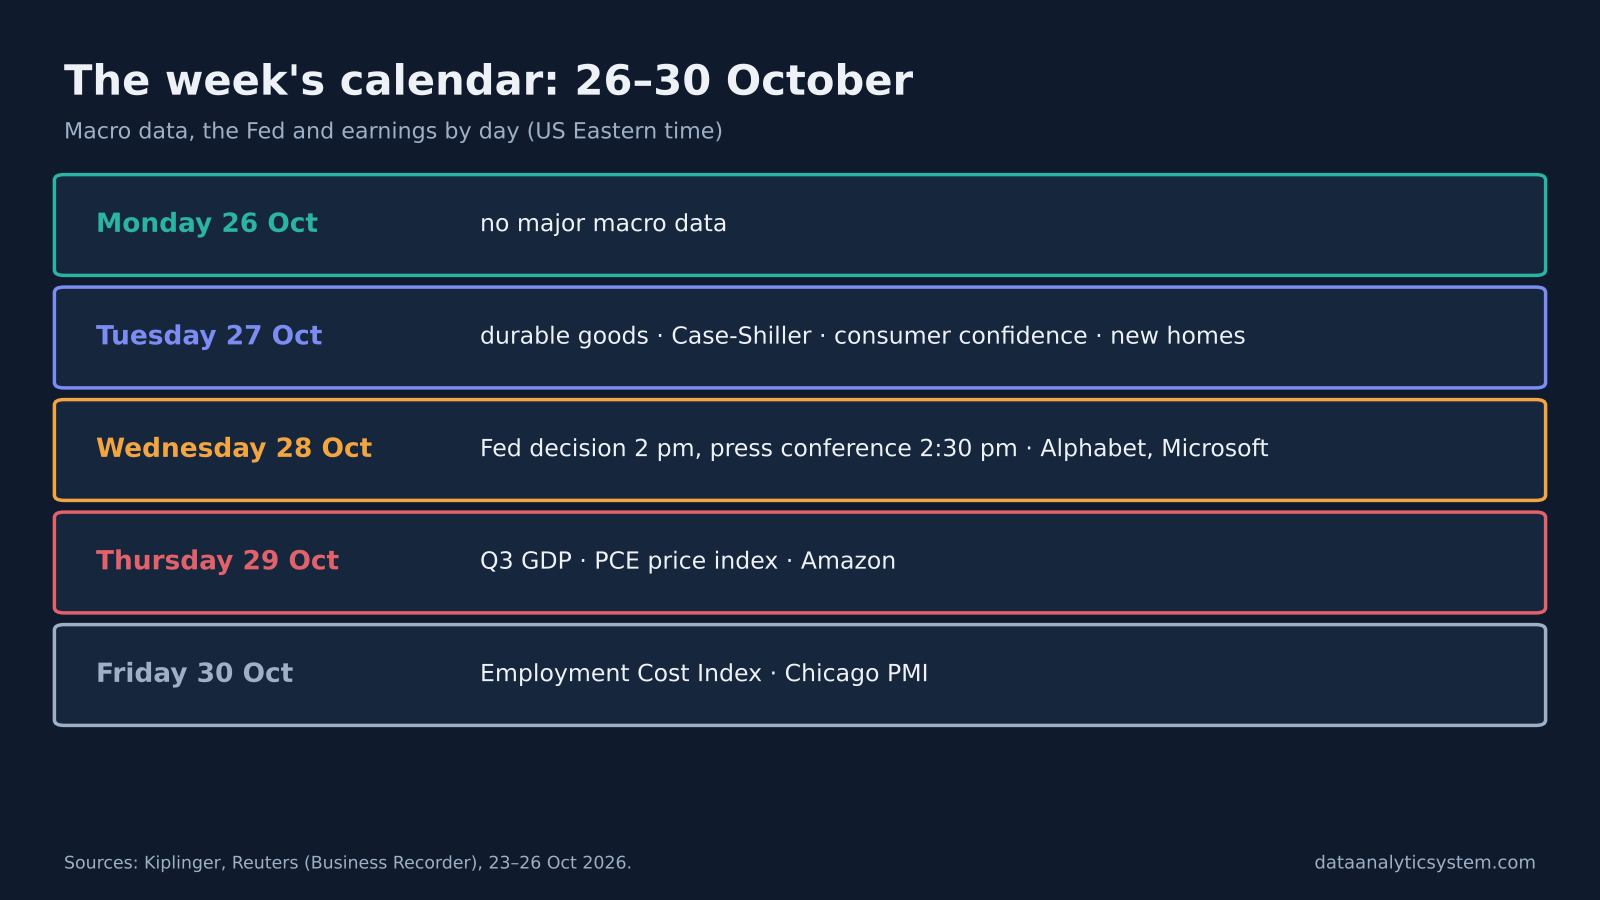
The week's calendar
Based on Kiplinger and Reuters (US Eastern time):
| Day | Data and events |
|---|---|
| Monday 26 Oct | no major macro data |
| Tuesday 27 Oct | durable goods orders, Case-Shiller home prices, consumer confidence, new home sales |
| Wednesday 28 Oct | trade balance; Fed decision 2:00 pm, press conference 2:30 pm; Alphabet, Microsoft earnings |
| Thursday 29 Oct | Q3 GDP, PCE price index and core PCE, personal income and spending; Amazon earnings |
| Friday 30 Oct | Employment Cost Index, Chicago PMI; Mary Daly and Alberto Musalem speak |
According to Reuters, Intel, Sandisk, Eli Lilly, Exxon, Chevron and Caterpillar also report this week. More than 100 S&P 500 companies had already reported before the week began.
The US changes its clocks on 1 November, so this week US Eastern time is only five hours behind Central European time.
The backdrop: what happened last week
According to Reuters, on Thursday the Nasdaq Composite had its biggest one-day drop since June, after investors were disappointed by quarterly reports from Meta and Lam Research. The S&P 500 is up about 12% so far in 2026. The article says strong profit growth has supported stocks this year despite spiking Treasury yields and higher energy costs linked to the Middle East conflict.
Capital spending by the large cloud providers (hyperscalers) is expected to reach about $800 billion this year, according to the article. That is why Alphabet's, Microsoft's and Amazon's numbers are watched so closely.
The Fed: what "a 5% chance" means
In September the Fed, according to Reuters, raised rates for the first time since 2023, to fight above-target inflation. Most investors do not expect another hike on Wednesday: fed funds futures pricing late on Thursday showed about a 5% chance of a hike at this meeting and about 80% for December.
Where does that number come from? The price of a fed funds futures contract implies the average policy rate the market expects for a given month. From that, one can work back to how likely participants consider each decision. It is market participants' current expectation, not a statement by the Fed, and it can change daily. Kiplinger's 23 October update, for example, showed an 88% chance of no change – the two sources measured at different times.
According to Reuters, investors doubt the Fed would hike a week before the 3 November midterm elections. Walter Todd, chief investment officer at Greenwood Capital, will watch Warsh's press conference for hints about the rate path.
Earnings: what to look at
In a quarterly report, news coverage usually highlights three numbers: revenue, earnings per share (EPS) and the company's own guidance for the next quarter. According to the experts quoted by Reuters, capital spending will be the fourth key figure this week: King Lip, chief strategist at BakerAvenue Wealth Management, says results will decide whether the tech selloff is temporary. Kevin Mahn, chief investment officer at Hennion & Walsh, says the reports will also show how long AI-related spending continues.
5 things many people don't know
- The "chance" is a price, not a vote. Fed-decision probabilities are calculated from futures pricing and can change within hours.
- PCE is the Fed's preferred inflation gauge. Thursday's PCE price index covers September; the Fed measures its inflation goal against it.
- The press conference comes half an hour later. The decision is at 2:00 pm and Warsh's briefing at 2:30 pm Eastern time.
- 32% is not true of every company. The LSEG figure is aggregate S&P 500 profit growth; individual companies can differ in either direction.
- Two clock rules in one week. Europe changed on 25 October and the US changes on 1 November, so this week the gap is five hours instead of the usual six (this article's conversion).
Summary
- Wednesday: Fed decision, Warsh press conference; Alphabet, Microsoft earnings.
- Thursday: GDP, PCE; Amazon earnings.
- Futures priced about a 5% chance of a hike on Wednesday and about 80% for December.
- Expected Q3 S&P 500 profit growth is above 32%.
Related reading: The Fed decision, 28 October · US inflation at 3.7%: what's in the basket · Four earnings reports in one week · Blog archive.
Educational content. Not investment advice and not a rate or price forecast. Data Analytic Investments is not affiliated with the Federal Reserve or the companies and portals cited; names are used for identification only. Images labelled "AI illustration" are not photographs.
Continue on DAI
Explore Topics
Written by
Data Analytic Investments
Content creator and writer sharing insights and stories.