Real Estate in 2026: What the Numbers Actually Say — and Why a Budapest Data Desk Is Open to New Partners
House prices are rising again across the EU, the world's central banks have stopped cutting, and Hungary's market is moving faster than most of Europe. We pulled the dated, sourced figures — Eurostat, KSH, the ECB, the Fed, Knight Frank — into one place, and we explain what a small Budapest data company can offer real-estate professionals who want their numbers read, not sold.
Budapest, 9 September 2026. If you work in property — as an agent, a developer, a landlord, an appraiser or an investor — you have spent the last three years reading two kinds of texts: press releases that say everything is fine, and forecasts that say everything is about to change. This article is neither. It is a dated, sourced reading of what the public statistics say about housing in the EU, the United States, the wider world and Hungary in 2026, written by a small data company in Budapest that measures markets for a living and does not sell property.
Every figure below has a date and an institution behind it. Where we could not verify a number from a primary source before publication, we say so instead of guessing. That is the whole method of our research desk — and it is also the reason we are writing this piece: we are opening our door to real-estate partners, and we want you to see how we work before you decide.
Europe: prices are rising again, rents too
The most recent EU-wide reading comes from Eurostat. In the first quarter of 2026, house prices across the European Union were 5.1 percent higher than a year earlier and 1.2 percent higher than in the previous quarter. Rents rose 3.0 percent year on year over the same period. Those are the official numbers published on 2 July 2026; the second-quarter release was not yet available when this article was written.
Behind the EU average there is a wide spread. Poland's house-price index, which Eurostat compiles and Trading Economics republishes, stood 5.9 percent above its level of a year earlier in March 2026, up from 4.3 percent in the previous reading. Hungary, as we show below, is running well ahead of that. We did not locate a standalone, dated figure for Germany or the United Kingdom that met our sourcing standard before publication, so we leave those countries out rather than quote a blog.
The world: nominal gains, flat in real terms
Knight Frank's Global House Price Index, which tracks 55 markets, is the broadest regularly published comparison. Its latest reading available to us covers the third quarter of 2025: a weighted average nominal rise of 2.4 percent, which becomes a fall of 0.1 percent once inflation is stripped out. In other words, on a global scale, houses were not really getting more expensive at the end of 2025 — they were keeping pace with everything else.
The extremes are instructive. Turkey led the table with a nominal rise of 32.2 percent that shrinks to 0.8 percent in real terms, a textbook illustration of an inflation economy. Portugal posted 17.7 percent nominal growth, placing it among the top three worldwide; Spain and Hungary were both cited by Knight Frank as having nominal gains above ten percent, although the exact figures were not in the excerpt we were able to verify. At the other end, Finland fell 9.5 percent, mainland China 5.5 percent, Canada 2.6 percent and Hong Kong 0.8 percent.
The United States is a separate story. The S&P Case-Shiller national index reported an annual gain for April 2026 — the latest release at the time of writing — but we did not open the release itself, so we do not quote the percentage. An earlier reading, for November 2025, was cited by Knight Frank at 1.4 percent. Dubai, often mentioned in the same breath as "global property," showed residential sales prices 6.09 percent higher year on year in April 2026 according to the REIDIN index as republished by Global Property Guide — apartments up 5.49 percent, villas up 9.86 percent, with a monthly dip of 1.76 percent. We flag that this is a secondary source.
Rates: the cutting cycle has paused
Property is priced off interest rates, and the two central banks that matter most have stopped moving. The European Central Bank left its deposit facility rate at 2.25 percent at its meeting on 23 July 2026, with the main refinancing rate at 2.40 percent and the marginal lending facility at 2.65 percent. The US Federal Reserve kept the federal funds rate in a range of 3.50 to 3.75 percent on 29 July 2026. We did not find a later 2026 decision from either institution before publication; both rates are quoted as of those dates. This is the kind of thing our Market Observation desk tracks daily for crypto and traditional markets alike: the data is real-time and sourced, and it is data, not a forecast.
What this means for housing is simple to state and hard to feel: borrowing is no longer getting cheaper by the quarter. Markets that rose on the expectation of further cuts now have to justify their prices with income, rents and demand.
Hungary and Budapest: the fastest-moving market we can verify
The Hungarian Central Statistical Office (KSH) publishes a quarterly house-price index that is, for our purposes, the most reliable local number. In the first quarter of 2026, Hungarian house prices were 8.6 percent higher than a year earlier in nominal terms and 6.7 percent higher in real terms — well above the EU average of 5.1 percent. The quarter itself was softer: prices fell 2.5 percent nominally and 3.0 percent in real terms against the last quarter of 2025, which is worth remembering when someone shows you only the annual figure.
For Budapest, KSH gives an average of 1.2 million forints per square metre across all dwelling types in the first quarter of 2026, and an average total price of 69 million forints per dwelling. The composition matters: family houses averaged 0.9 million forints per square metre (up 4.9 percent year on year), prefabricated "panel" flats 1.2 million (up 18 percent), and flats in traditional apartment buildings 1.3 million (up 7.8 percent). Geographically, the outer and transitional districts rose around ten percent year on year, while the inner Pest districts and the Buda foothills rose between 4.6 and 5.8 percent. The cheapest segment of the city moved the fastest.
There is a policy reason for that. On 31 July 2025 the government issued Decree 227/2025 establishing the Otthon Start program: a state-subsidised mortgage at a fixed 3.00 percent, with a general cap of 50 million forints, sub-caps of 100 million for flats and 150 million for houses, a maximum term of 25 years, a purchase-price ceiling of 1.5 million forints per square metre, and eligibility limited to applicants who have not owned a home in the previous ten years. We have read the decree itself; we have not verified the press claims about record lending volumes or a 3,000-billion-forint mortgage market in 2026, so we do not repeat them as fact. But a 3 percent fixed rate in a country whose central bank rate is far above that, combined with a price ceiling that sits exactly where the panel and outer-district market lives, explains the 18 percent panel figure better than any narrative about "investor demand."
Cross-border money: the data lags the headlines
Everyone in this business has heard that international capital is "back." The most recent hard figure we could verify from CBRE covers the first half of 2024: global cross-regional real-estate investment of 26.7 billion US dollars, down ten percent year on year, with Europe attracting 18.4 billion (up 30 percent), North America 5.25 billion (down 58 percent) and Asia-Pacific 3.16 billion (up 1.6 percent). CBRE's page adds only a qualitative sentence about rate cuts supporting 2025 and 2026. We found headlines claiming double-digit growth in 2026 volumes, but no primary source, so they stay out of this article.
Two structural themes deserve a line each, with the same caveat. First, the EU's revised Energy Performance of Buildings Directive sets progressive renovation trajectories: according to the EU's BUILD UP explainer, at least 16 percent of the worst-performing non-residential floor area must be renovated by 2030 and 26 percent by 2033, and the residential stock must cut average primary energy use by 16 percent by 2030 relative to 2020. Before you build a business plan on the exact years, read the directive text; we have read the explainer, not the Official Journal. Second, real-estate tokenisation under the EU's MiCA framework is being described across the industry as entering a "breakout phase" in 2026. We write about MiCA regularly — our company is explicitly not a crypto-asset service provider under it — and we note that every source we found on property tokenisation was an industry blog, not a regulator. That is a topic for our Insights series, where the rule is the same: a claim without a document is a question, not a fact.
Who we are, and what we are offering property professionals
Data Analytic Investments is a Budapest company registered in August 2026, with one human decision-maker and four AI systems that structure, challenge, build and watch: Sol, Vera, Faber and Argus. We are an educational and market-information service. We do not manage money, we do not sell property, and we do not tell anyone what to buy. What we do is measure — every claim gets a date, every source gets a link, and the final word is always human.
That discipline was built for crypto markets, where it is badly needed. Our Market Observation desk publishes sourced daily readings; our Uncle Sunny Academy and Crypto Academy teach people to read a chart and a balance sheet before they touch either; The Analyst Room is where the longer studies live; and our documentary book on Ripple and the XRP Ledger exists in four languages because we wanted one thoroughly sourced account of a company most people only know from headlines. We even apply the same method to sport, because a football table is a dataset too.
Real estate is the natural next step, and we are not going to pretend we can do it alone. We know statistics, data pipelines, multilingual publishing and the tedious work of checking a number against its source. We do not know your street, your district, your buyers or your building. So we have opened a partner program with three levels, from a free listing to a premium presence, for agencies, developers, valuers, property managers and international brokers who want a research desk behind their name rather than another marketing agency in front of it. Our premium real-estate partner will introduce themselves here shortly; until then we would rather show you our method than describe theirs.
If you are reading this from London, Vienna, Dubai, Lisbon or Warsaw: Budapest is a market where, on the official numbers, prices are rising faster than the EU average, a subsidised 3 percent mortgage is reshaping the lower end, and the per-square-metre price of the capital is still a fraction of Western European capitals. Whether that is an opportunity or a warning is exactly the kind of question we do not answer for you. We give you the dated data and the method to read it — and, if you want a partner in Budapest who works that way, the door on the partners page is open.
Sources, all opened and dated on 9 September 2026 unless stated: Eurostat news release of 2 July 2026 (EU house prices and rents, Q1 2026); KSH, "Lakáspiaci árak, lakásárindex, 2026. I. negyedév"; ECB monetary policy decision, 23 July 2026; Federal Reserve FOMC statement, 29 July 2026; Knight Frank Global House Price Index, Q3 2025 (article dated January 2026); Trading Economics, Poland house-price index (Eurostat data), March 2026; Global Property Guide citing REIDIN, Dubai, April 2026; CBRE, "Global Cross-Regional Investment Volume Nears Stability" (H1 2024 data); Government Decree 227/2025. (VII. 31.) on the Otthon Start program, Hungarian legal register; EU BUILD UP platform explainer on EPBD minimum energy performance standards. Not verified before publication and therefore not quoted as fact: UK and German 2026 price releases, the exact Case-Shiller April 2026 percentage, 2025–2026 cross-border investment totals, press claims on Otthon Start lending volumes.
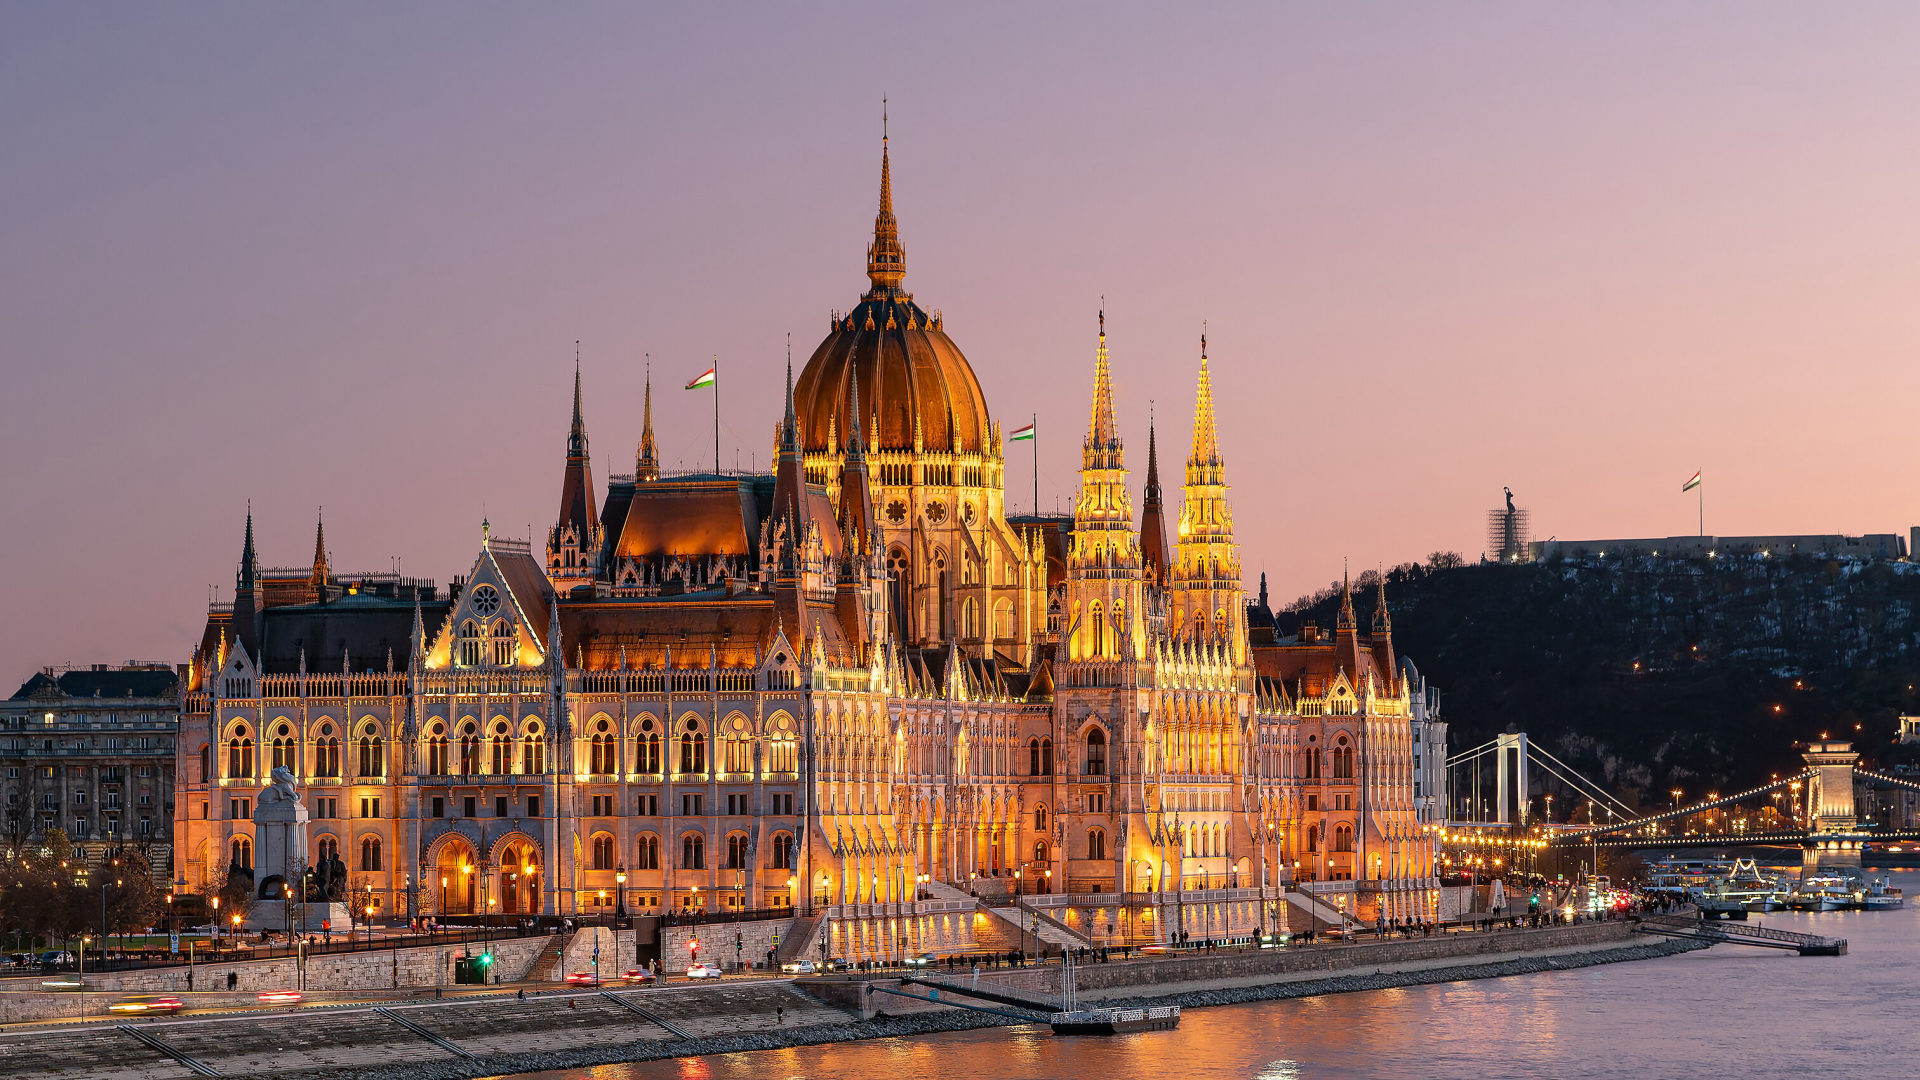
Cover image: the Hungarian Parliament and the Chain Bridge at dusk, Budapest, 23 November 2024. Photo: Jorge Franganillo, CC BY 2.0 (Wikimedia Commons), cropped to 16:9.
Educational content. Not investment advice. Data Analytic Investments Kft., Budapest — dataanalyticsystem.com
Continue on DAI
Explore Topics
Written by
DAI Research Desk
Content creator and writer sharing insights and stories.